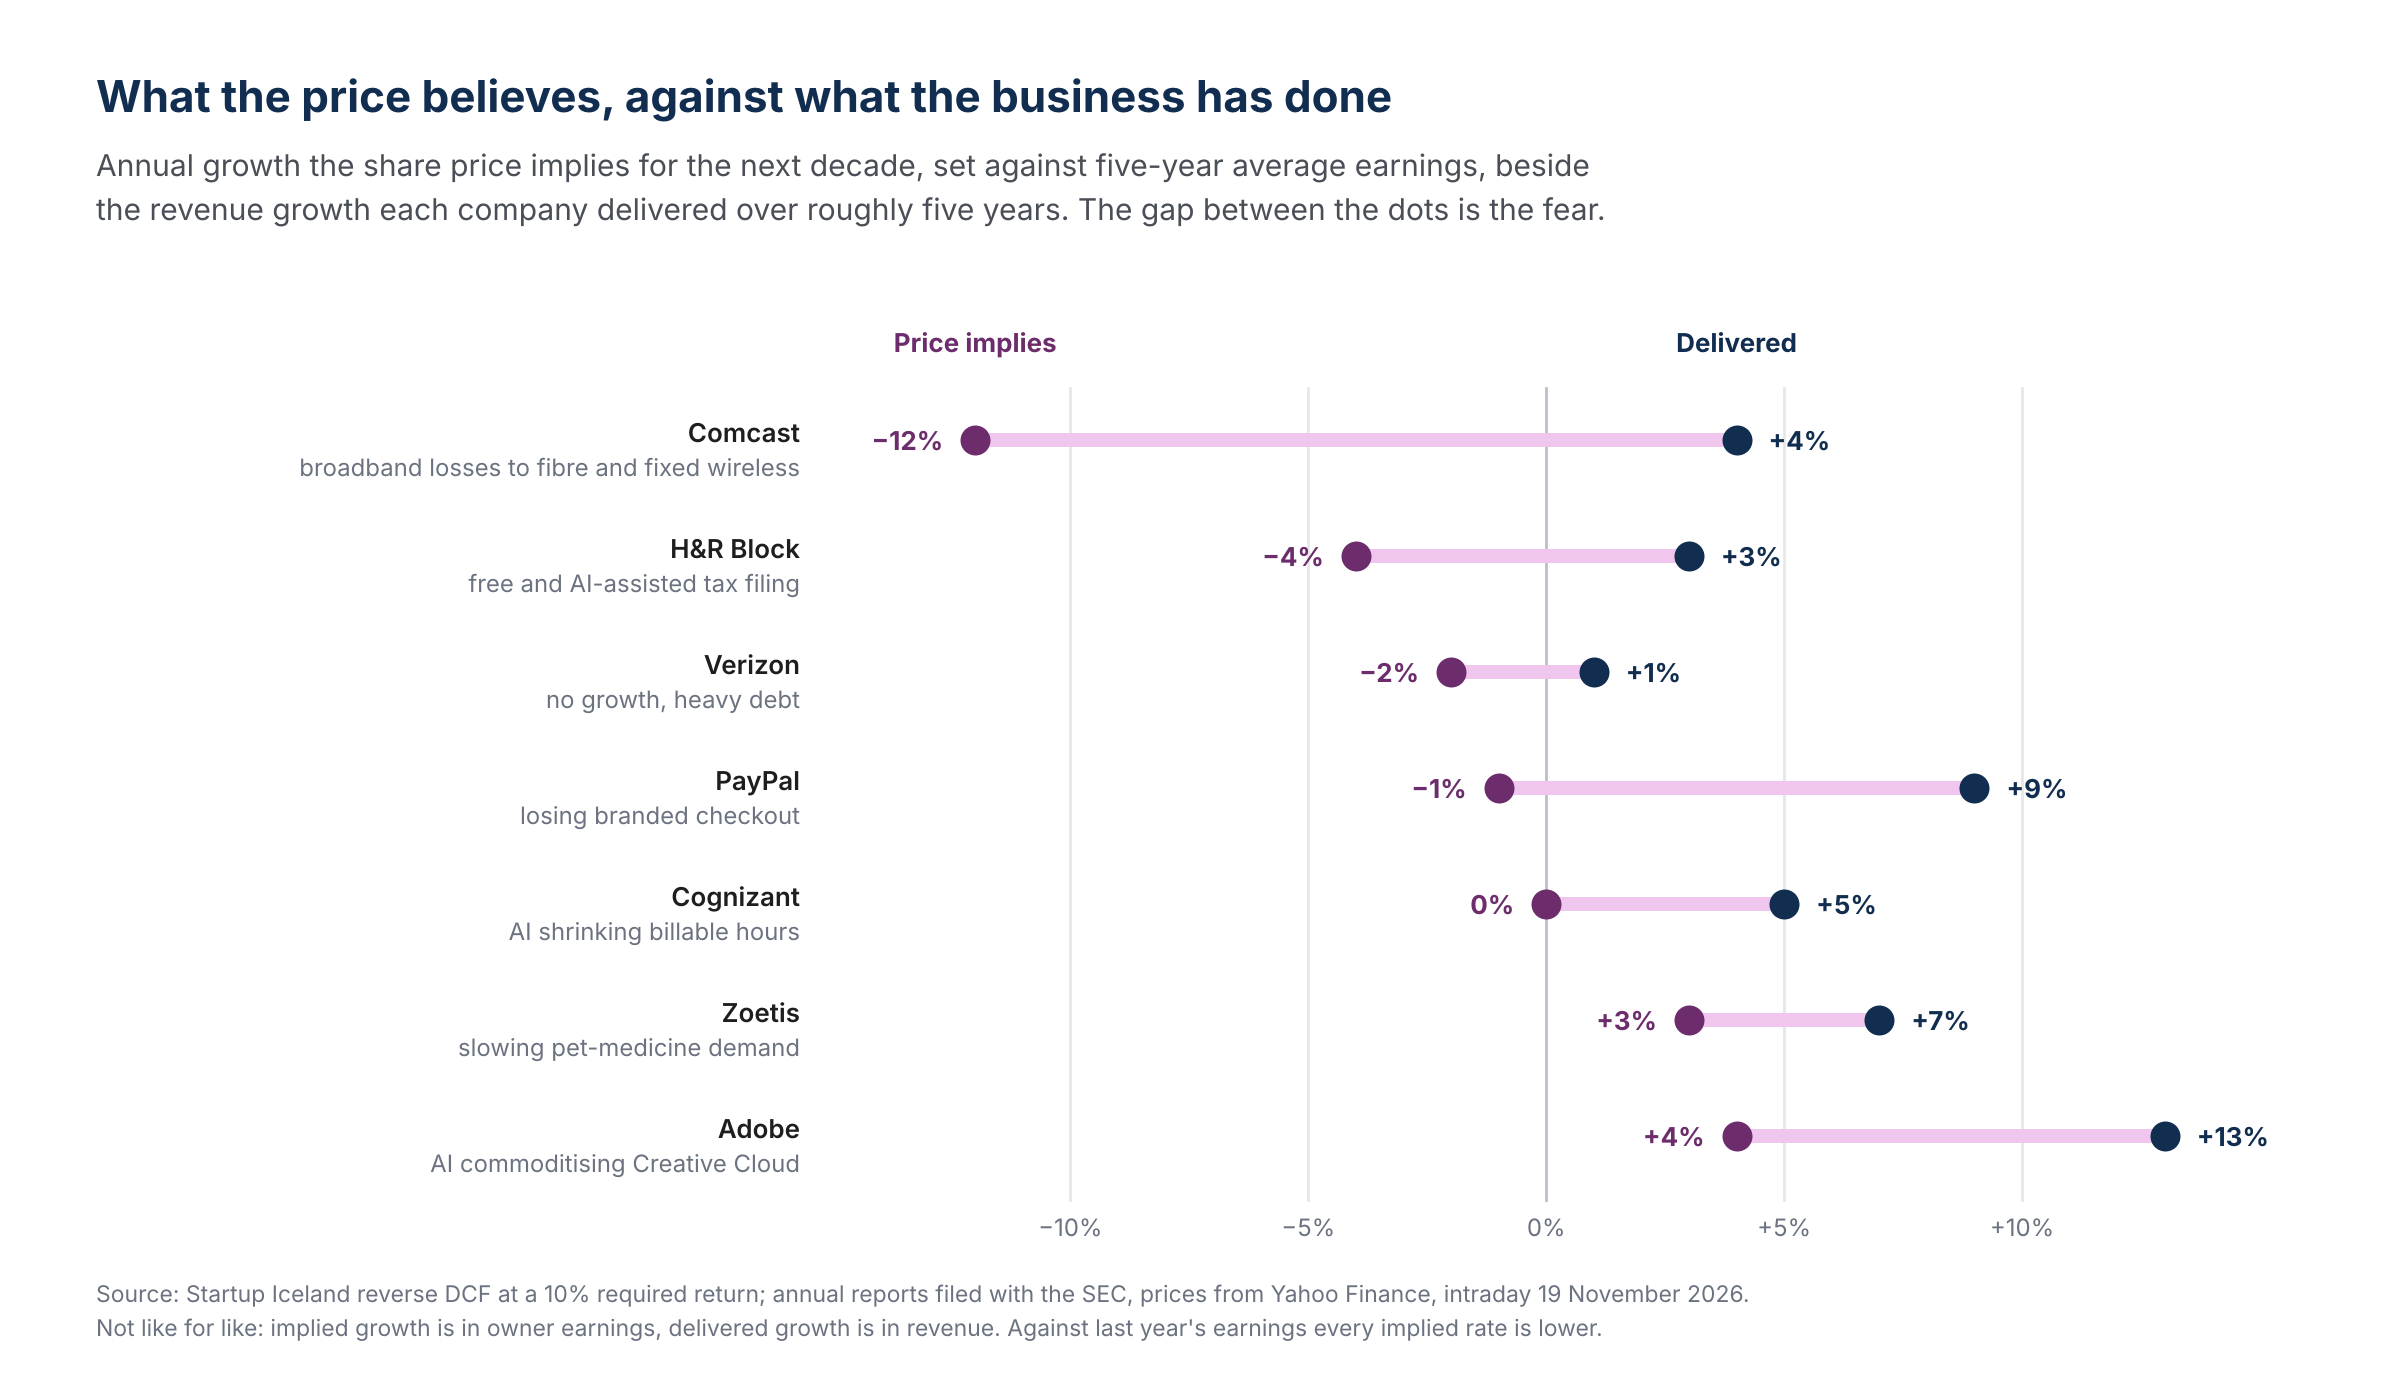
A screening of 1,734 US-listed companies found that, despite a broad market decline, stocks remain generally expensive. Only 19 high-quality companies traded at substantial discounts, narrowing to seven after excluding cyclicals and accounting distortions. Potential opportunities include Adobe, Cognizant, PayPal, H&R Block, Comcast, Zoetis, and Maximus, but each carries a specific, analyzable risk.
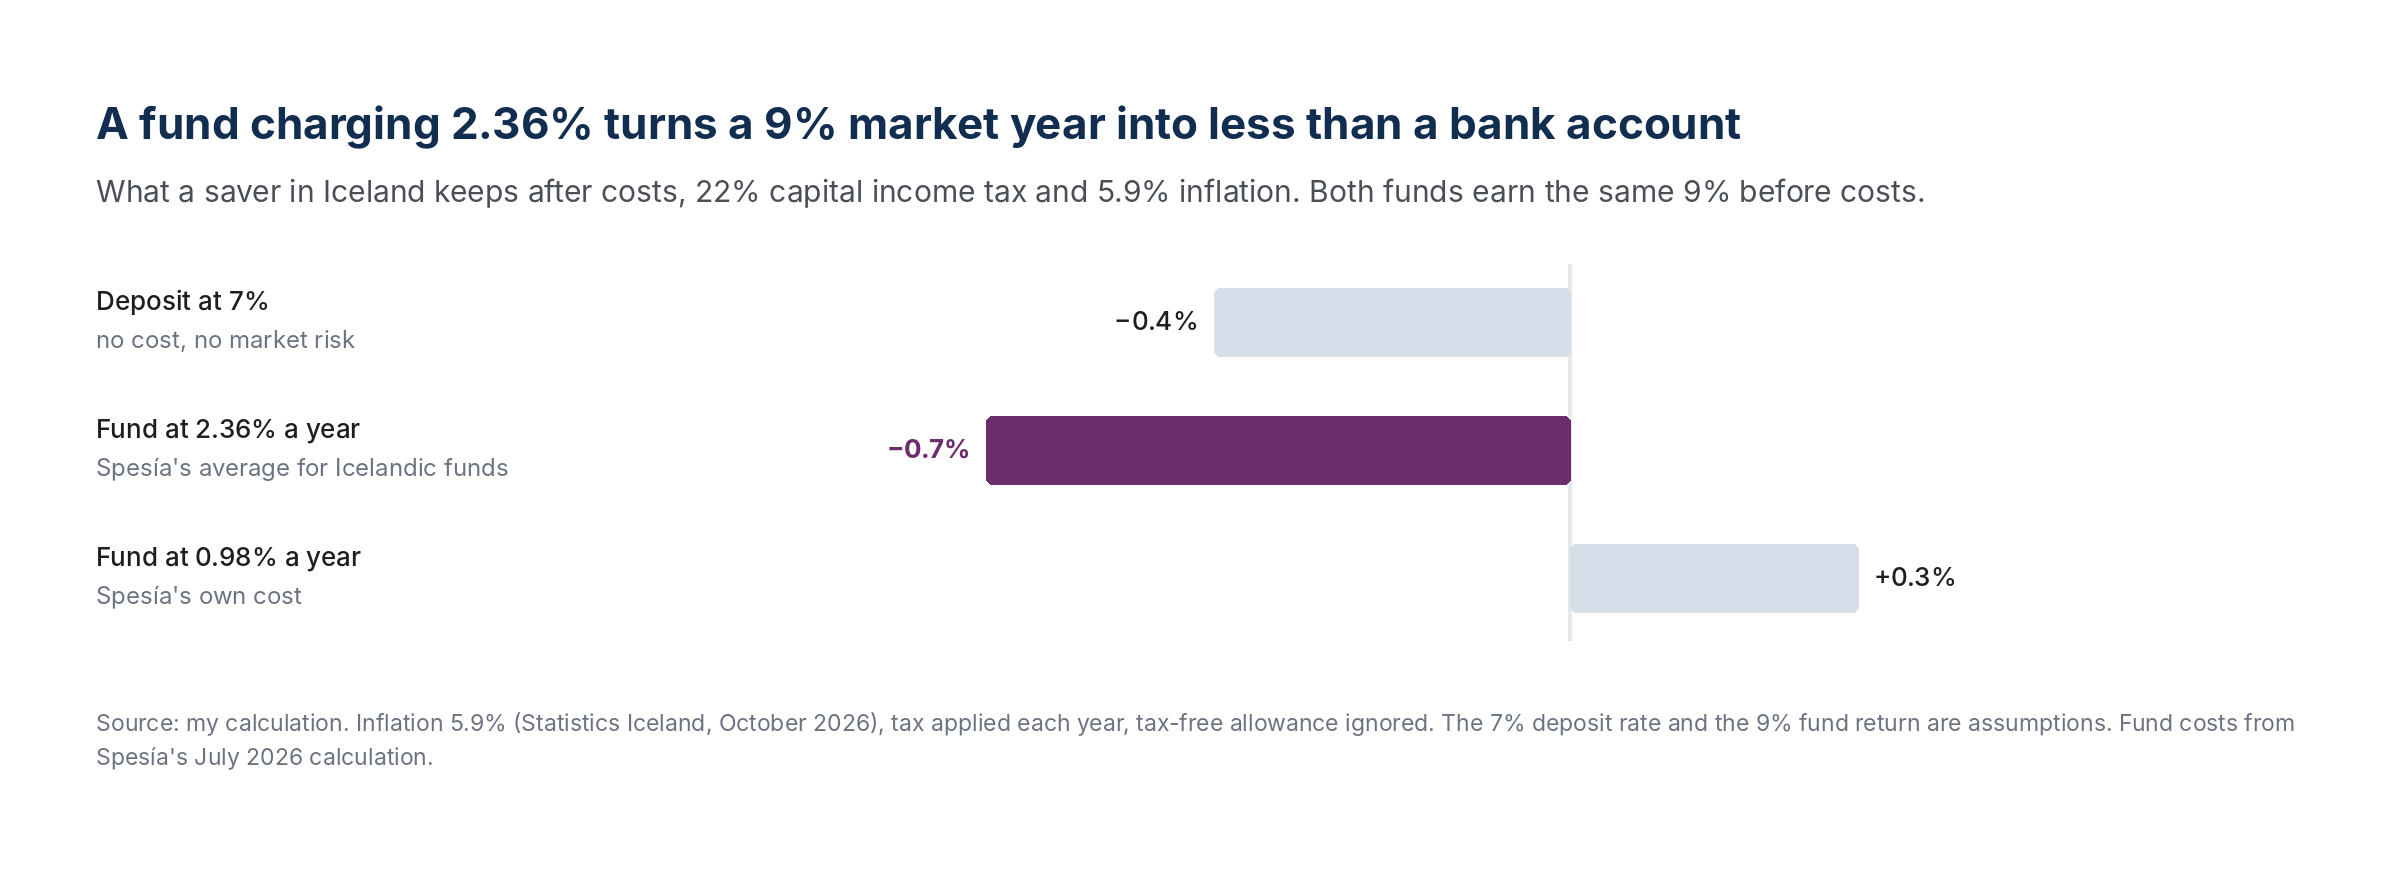
Icelandic savers must earn roughly 7.6% annually to preserve purchasing power after 5.9% inflation and 22% tax. High fund fees can consume most real returns, leaving investors worse off than bank deposits. Evidence shows Icelandic and European funds often charge heavily while underperforming benchmarks. Investors should compare total costs, after-fee performance, and risk horizon.
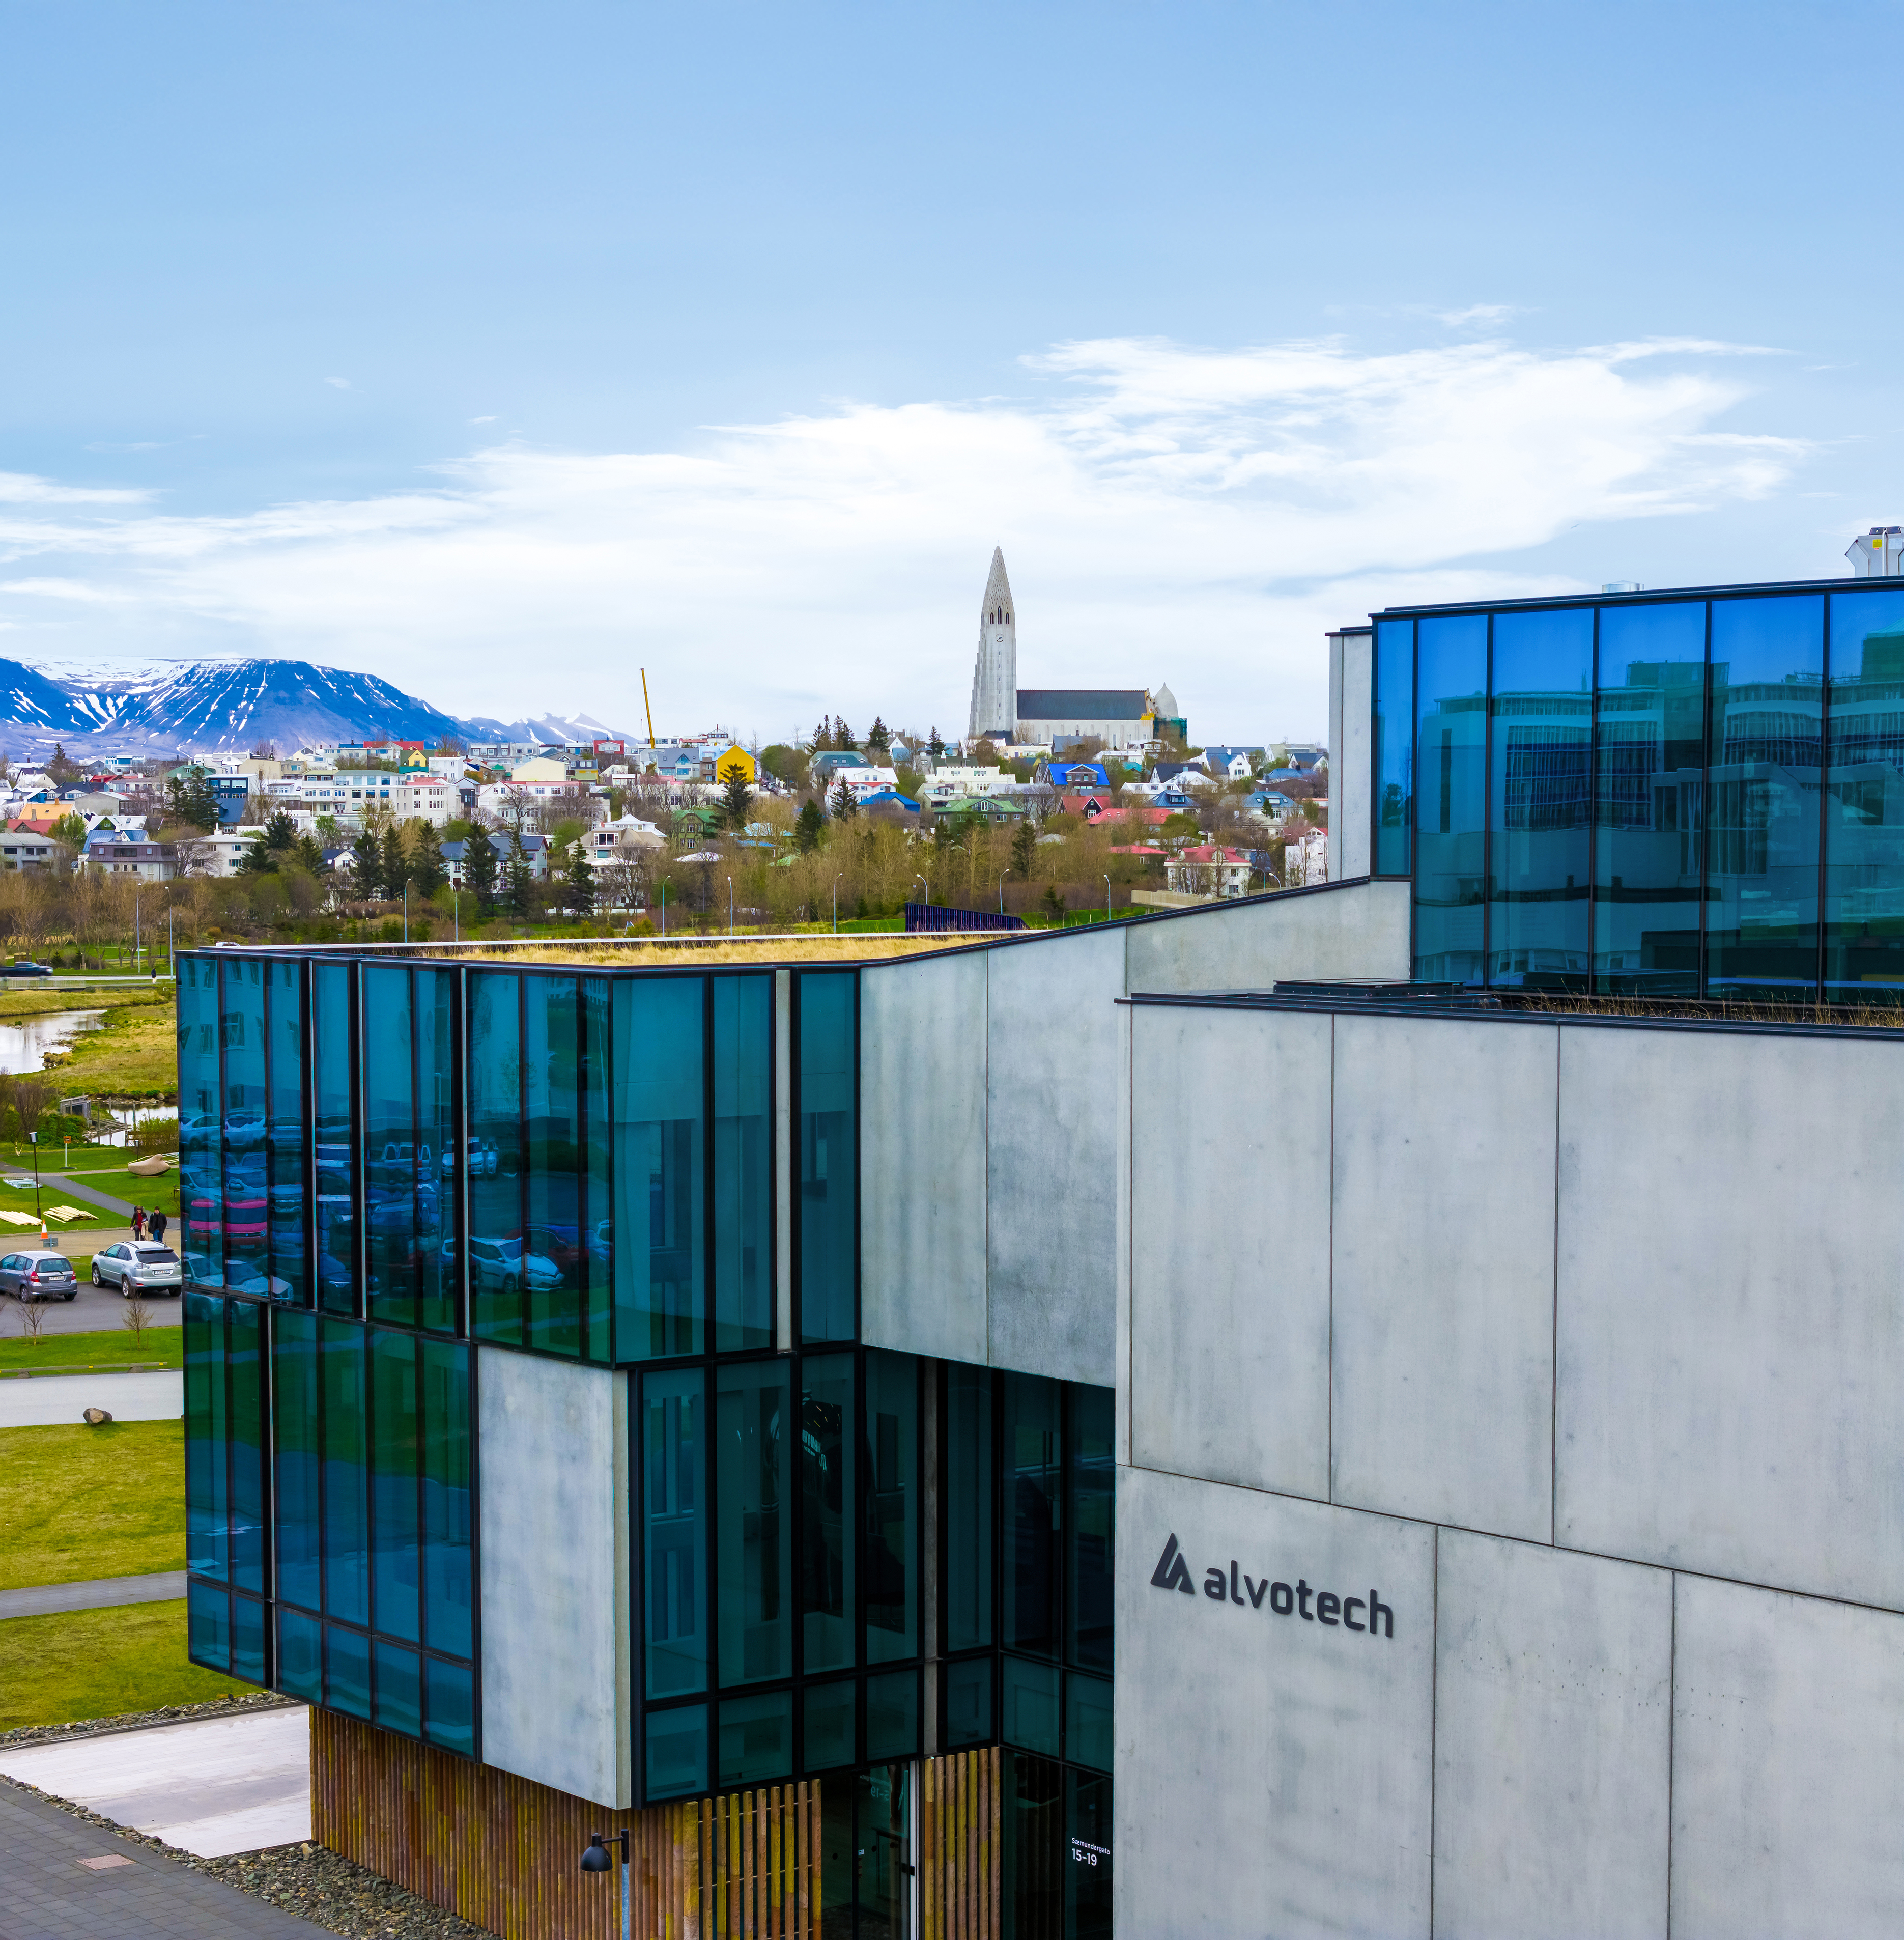
Alvotech’s Reykjavík factory is now FDA-approved and producing more efficiently, but revenue remains below expectations and cash is under pressure. Meeting 2026 guidance requires an exceptionally strong fourth quarter, potentially dependent on approvals and licensing deals. High debt, interest, investment, and working-capital needs make adjusted EBITDA misleading. Future focus: cash generation, contract assets, and financing risk.
The Blue Lagoon’s public offering values the combined company at about ISK 121 billion, assuming ambitious earnings growth. While its brand and unique asset are attractive, modest returns, debt, eruption risk, uninsured shutdown losses, VAT uncertainty, and unrestricted selling weigh heavily. The author estimates fair value at ISK 60–80, below the 95 krónur offer price.
Since October I have read every job ad posted in Iceland, every day. Not by hand; the Startup Iceland jobs …

On October 29, the Prime Minister’s Office released a progress report on Iceland’s industrial policy, showing four actions completed. However, only one of these was new, with concerns over two stalled initiatives in aquaculture and data centers. Key decisions regarding electricity allocation and metrics for success remain unaddressed.
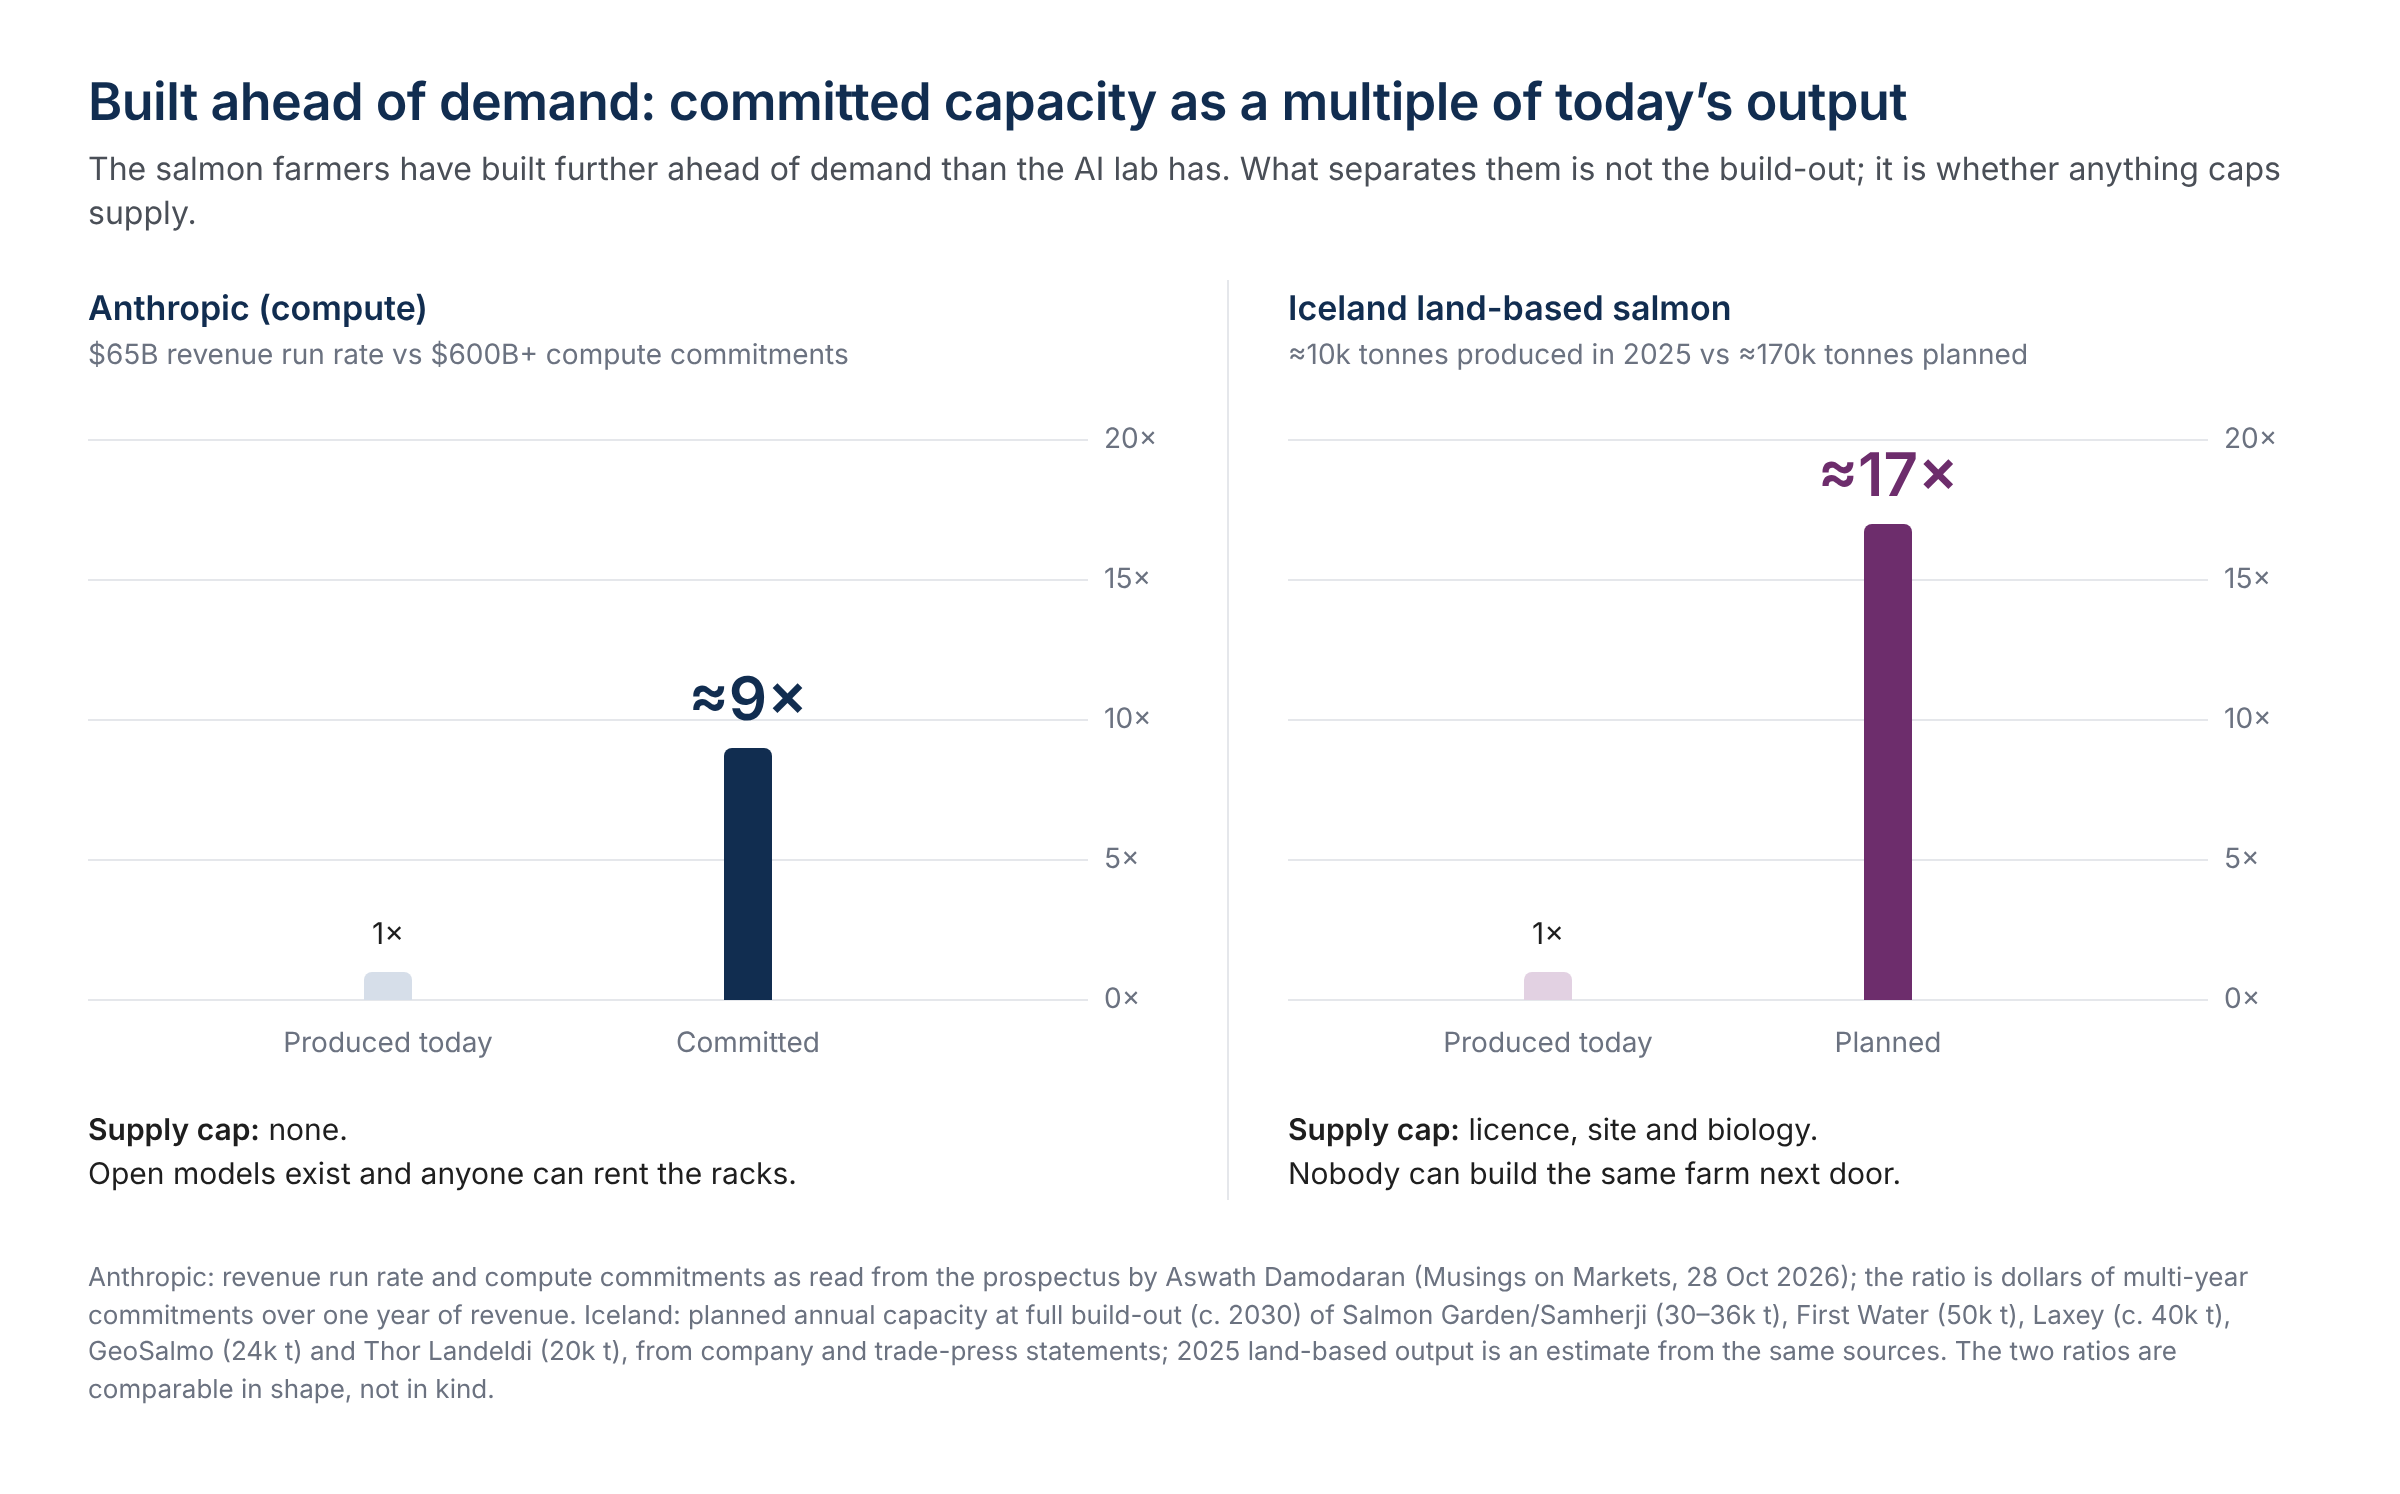
The analysis of Anthropic’s prospectus reveals that the company operates as a capacity business rather than a software one, driven by high compute costs that significantly exceed revenue. It draws parallels to Iceland’s capacity industries, emphasizing the importance of supply limitations. Ultimately, insight into Anthropic’s financial structure suggests strategic considerations for future capital allocation in the AI sector.
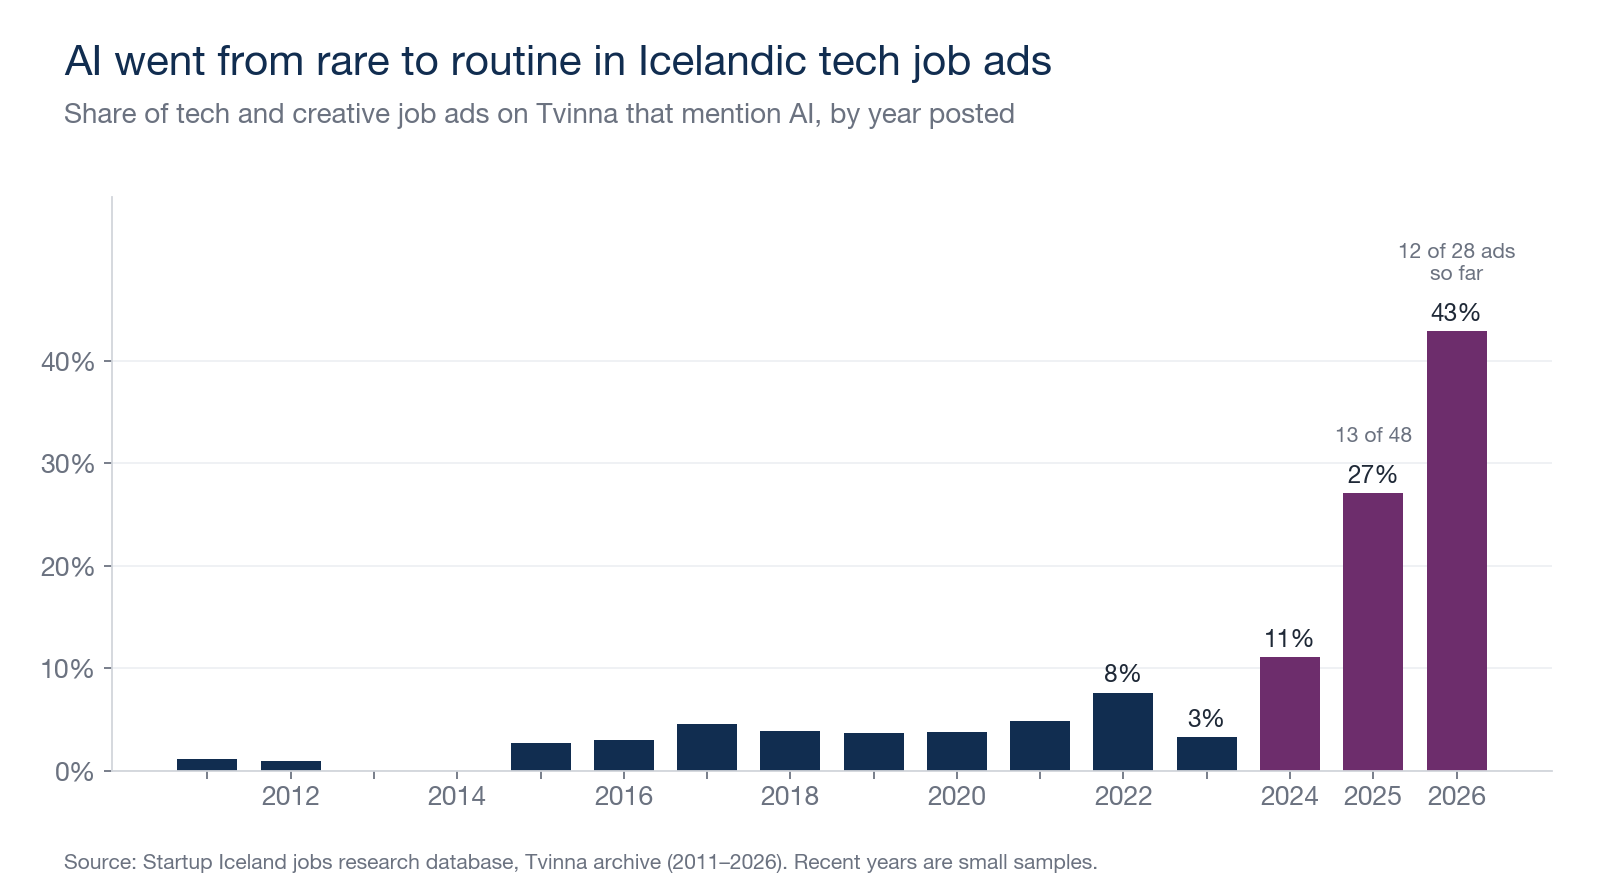
Conversations about AI in Iceland reveal widespread concern over job loss, yet data shows most open positions are in roles generative AI cannot perform, such as teaching and healthcare. Employers seek individuals skilled in AI use rather than AI specialists. Companies face a choice in integrating AI: reduce jobs or enhance productivity through task redesign.
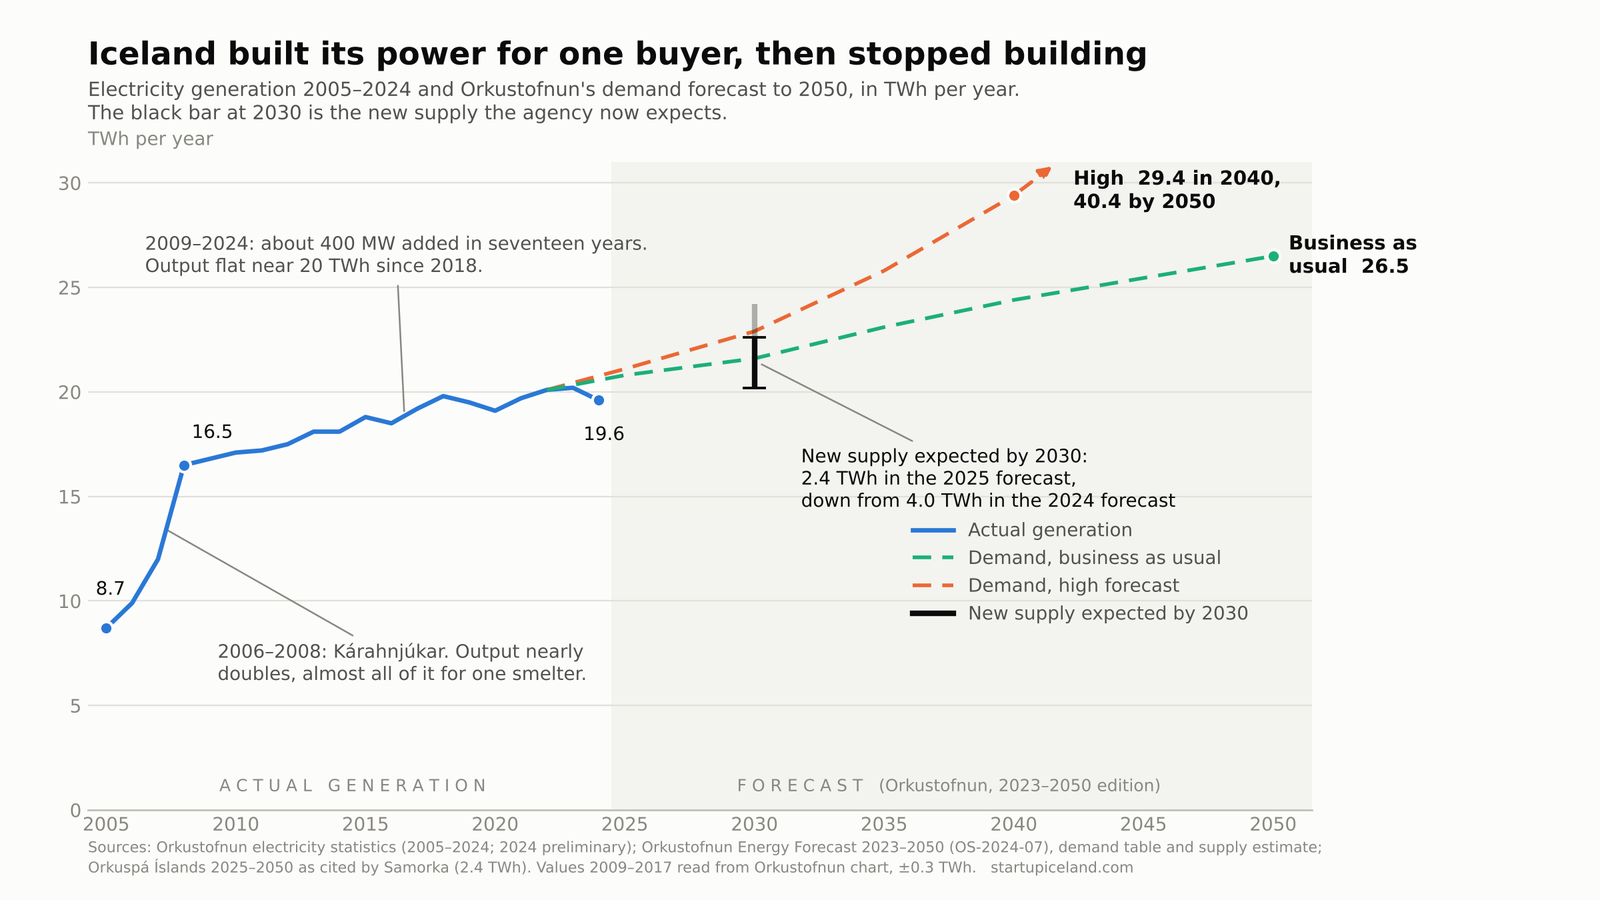
Iceland faces a critical juncture in electricity management as past practices of allocating power for specific customers shift towards a new model where demand exceeds supply. Following the resignations of key executives, the nation’s first industrial policy lacks clear guidelines for power allocation, igniting complex discussions on prioritizing energy use for future projects.

This piece starts from a chart about electricity and wealth that has been circulating, and uses Iceland to test it. …
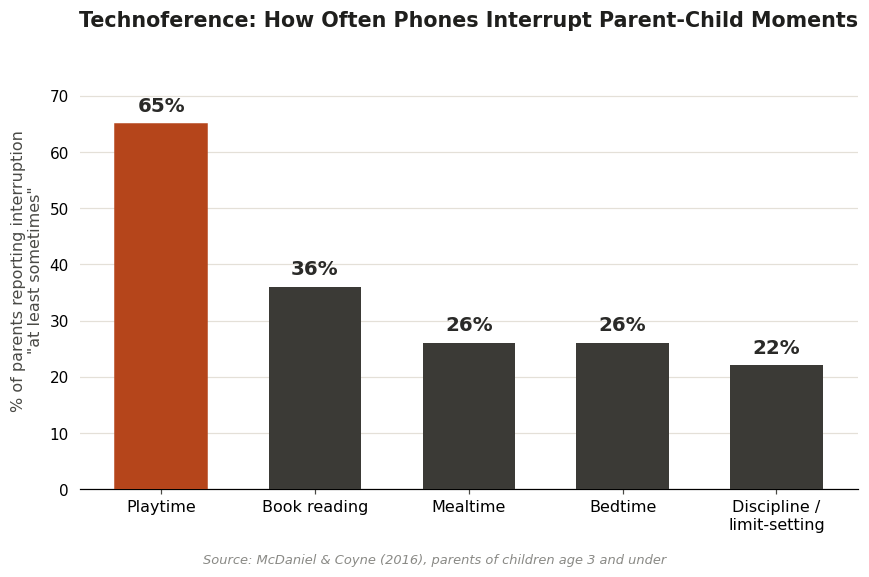
In 2025, all Nordic countries saw a decline in PISA scores, with Iceland experiencing the most significant drop. The core issue lies not in time scarcity but in a lack of genuine attention from adults. Self-belief in students often stems from the belief of mentors, emphasizing the importance of supportive relationships amid increased distraction from technology.

This article discusses the systemic risks in Iceland’s mortgage market, particularly focusing on the unfair distribution of risks between borrowers and lenders. It argues for a redesign of the mortgage system, advocating for a shift from indexed loans to a structure similar to Denmark’s model, which fairly allocates risks and promotes financial stability for households.

This is the first in a series on the problems Iceland now has to solve at home — the ones …
A personal reflection, offered especially to anyone here who has grown bitter — about the closed doors, the connections they …
On the morning of 30 August 2026, Iceland gave its answer. This is not a victory lap. It is a …
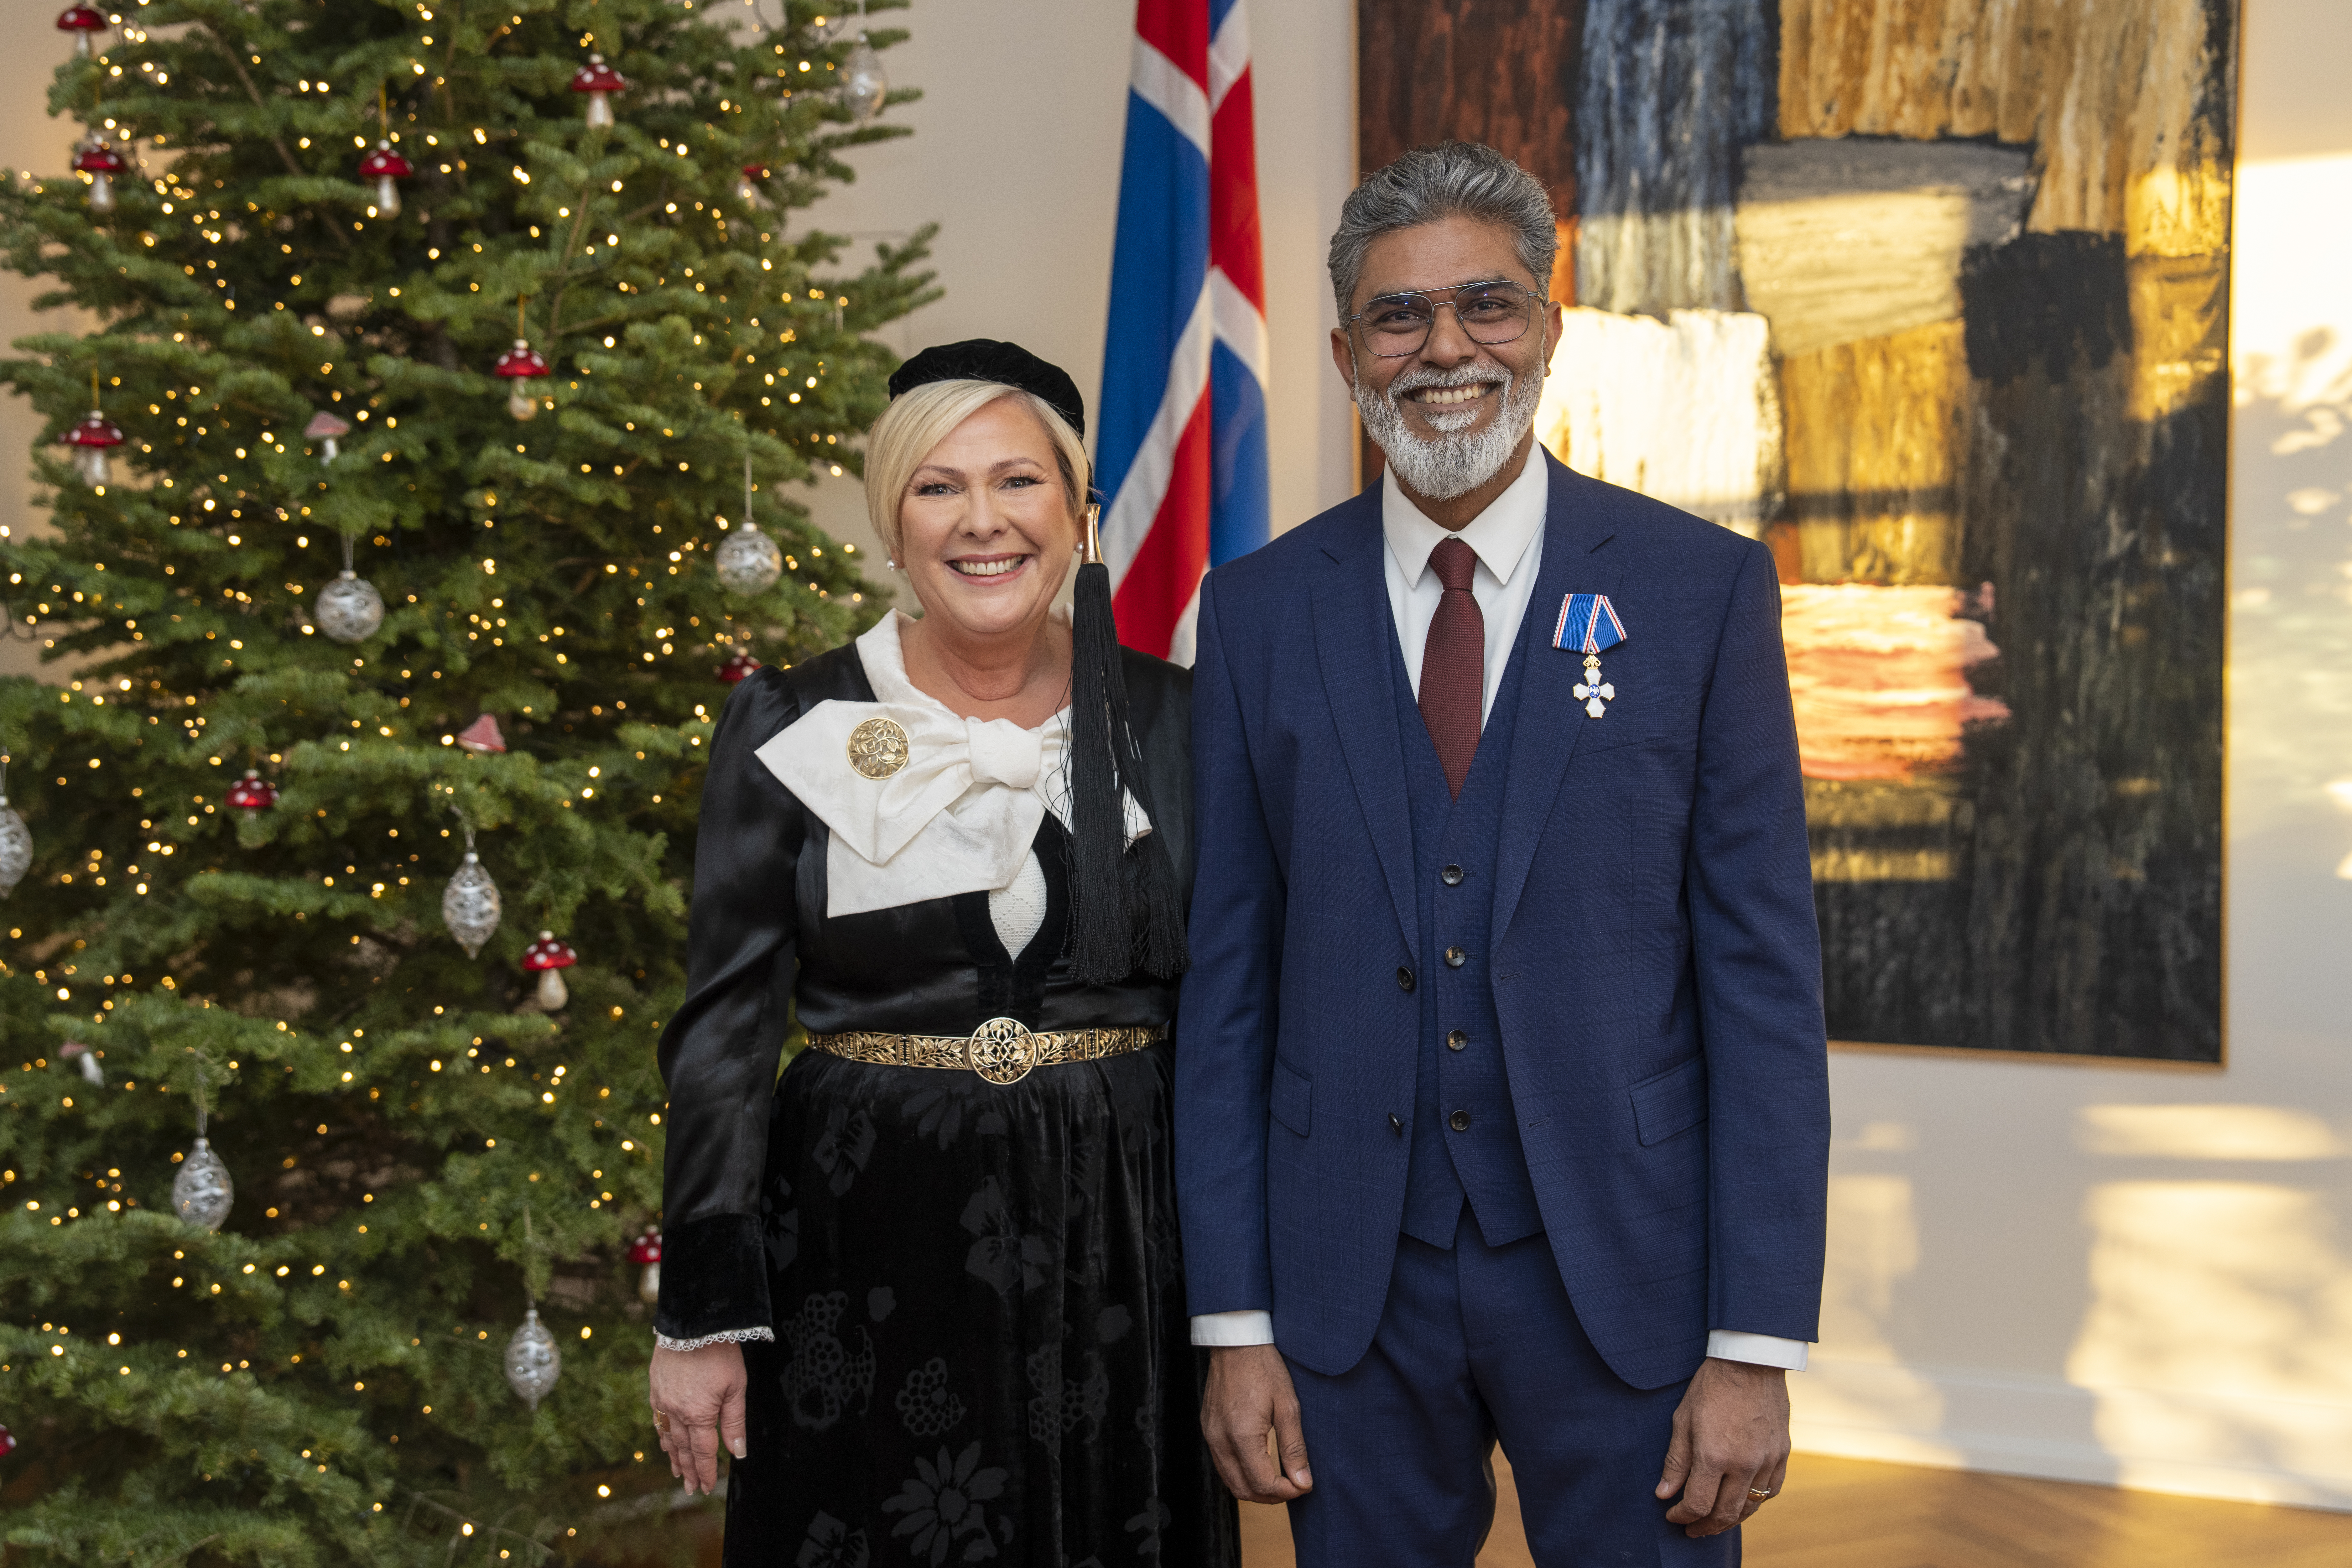
The author reflects on their dual identity, rooted in India but enriched by experiences in Iceland. After thirty years away, they found that their heritage didn’t diminish but instead informed their new life. Through relationships with inspiring Icelandic peers, they learned that belonging is not divided but compounded, creating a stronger, unified self.
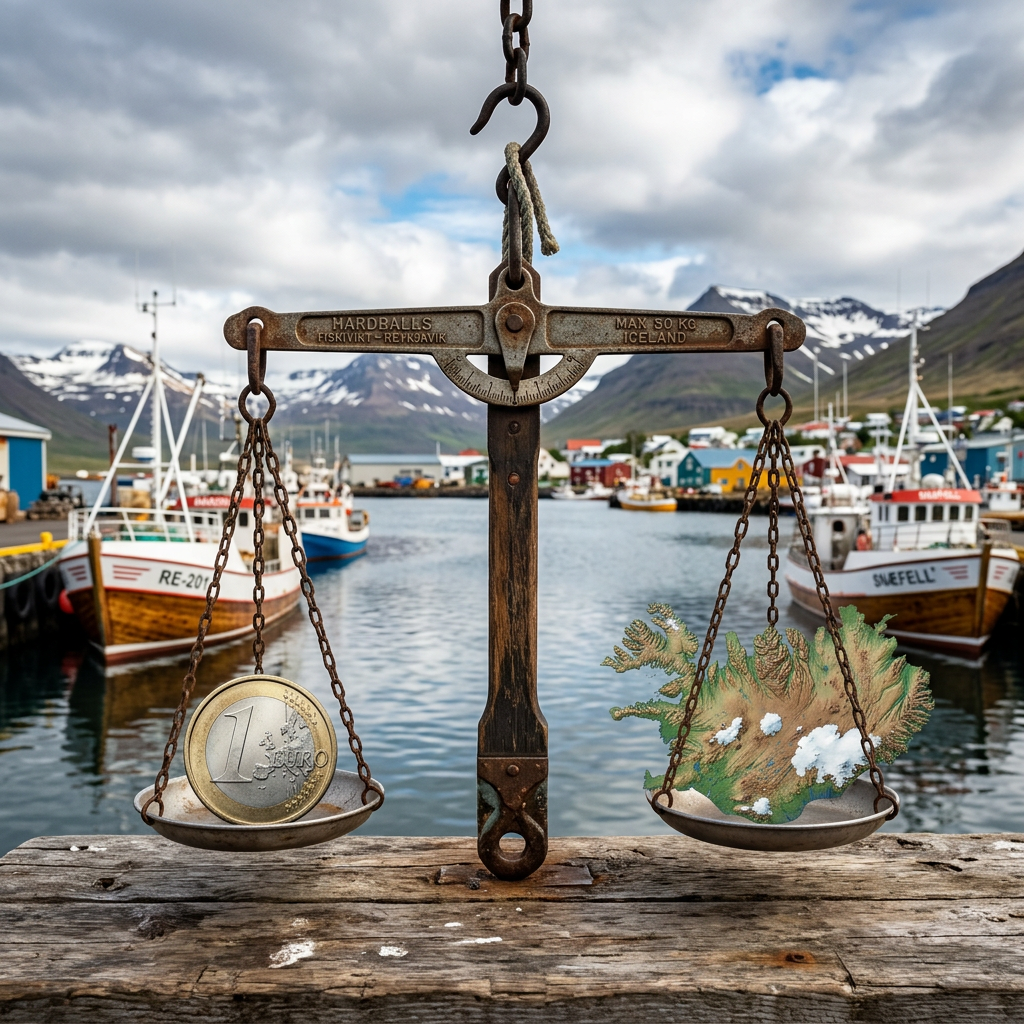
This article analyzes the financial implications of Iceland’s potential EU membership, revealing a significant disparity in estimated costs, ranging from 7 to nearly 50 billion krónur annually. It argues that Iceland would primarily be a net contributor, funding the development of poorer EU nations, and emphasizes the permanency and associated burdens of such a commitment.

Smári McCarthy wrote a detailed rebuttal to my post of 10 August, and this week he made a wider version …

I have spent this series arguing one side of Iceland’s referendum. That earns a reader’s suspicion, and it should. So …
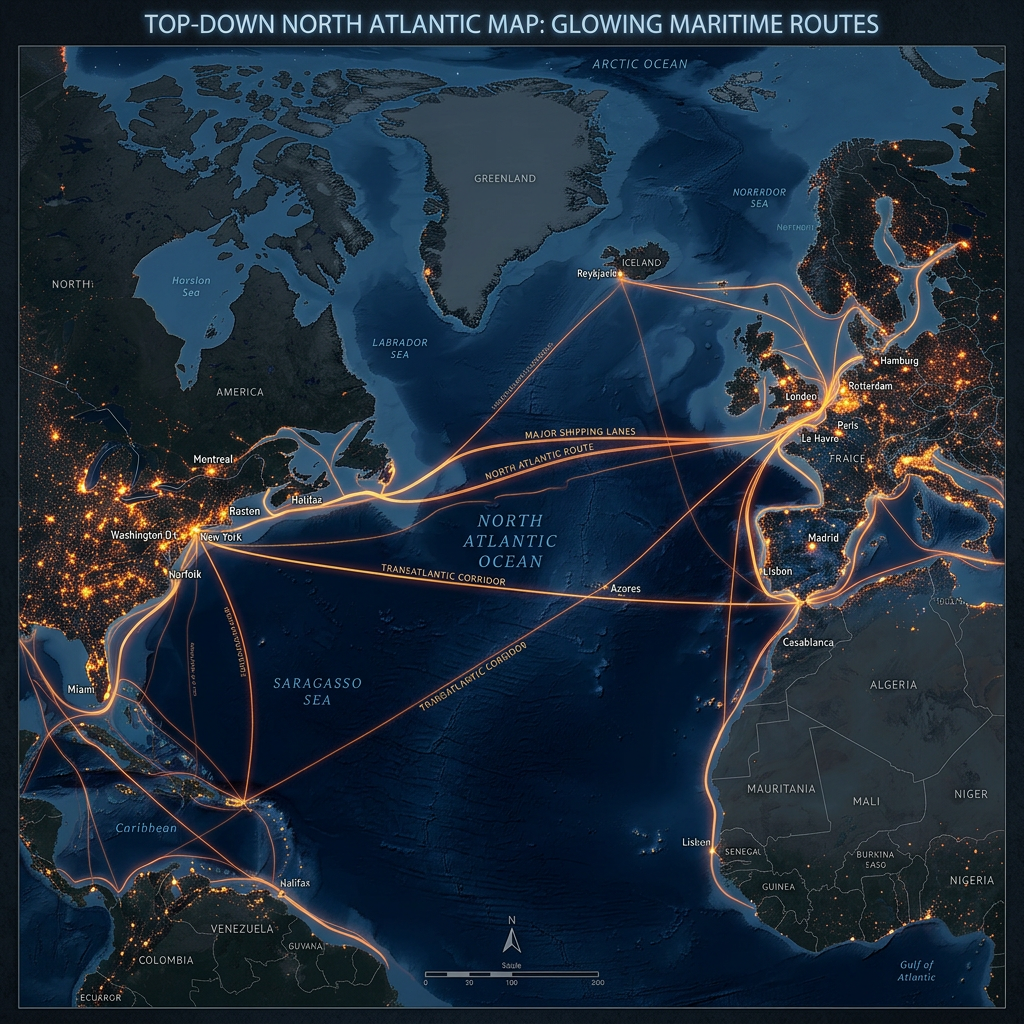
The article discusses Iceland’s strategic significance versus its economic relevance in the context of EU accession. While Iceland’s economy is minor within the EU, its geographic position is crucial for controlling the North Atlantic and observing Russian naval activity. The piece argues that Iceland’s security needs can be met through existing NATO affiliations and bilateral agreements, making EU membership unnecessary.

